 Marina Lyubimova
Deutsche Bank raised its price target for Meta Platforms (NASDAQ: META) to $820 from $750, an increase of $70, or 9.3%, while maintaining its Buy rating.
| Deutsche Bank | Previous | New |
| Price target | $750 | $820 |
| Change | — | +9.3% |
| Rating | Buy | Buy |
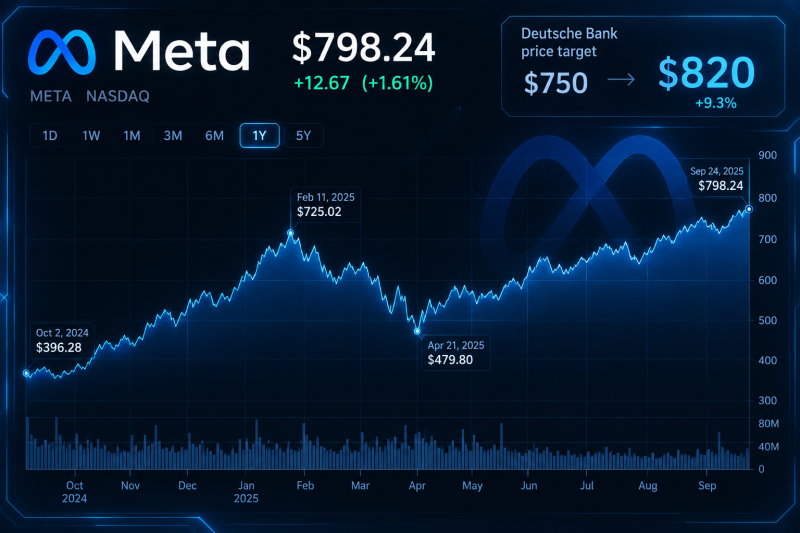
AI Returns Start to Offset Capex Concerns
The previous $750 target followed Meta’s Q2 2026 results and reflected concerns about rising AI infrastructure spending and limited visibility into 2027 capital expenditures.
Deutsche Bank’s earlier valuation was based on approximately 23× estimated FY2027 GAAP EPS, down from 24× previously.
The new $820 target points to greater confidence in potential returns from Meta’s AI investments.
Key drivers include:
- AI-powered improvements to advertising and recommendations;
- monetization of AI agents and subscriptions;
- potential revenue from model APIs;
- possible monetization of AI compute infrastructure.
Deutsche Bank Adds $70 to META Valuation
- $750 → $820
- Increase: $70 per share (+9.3%)
The main constraint remains Meta’s high capital intensity. Higher AI infrastructure spending can pressure free cash flow and margins if revenue growth does not keep pace.
Meta’s valuation increasingly depends on converting AI infrastructure spending into measurable revenue and earnings growth.
META Targets Move Above $800
Recent analyst revisions have pushed several META targets above the $800 level:
| Firm | Previous | New |
| Deutsche Bank | $750 | $820 |
| JPMorgan | $640 | $820 |
| Jefferies | $710 | $875 |
The key metrics are now AI-driven ad growth, AI product monetization, 2027 capex and returns on infrastructure spending.
 Marina Lyubimova